
Effective risk management with R
September 21, 2014
Conference
The first EARL Conference (Effective Applications of the R Language) was held 2014 September 15-17 in London.
Talk
My talk was “Effective risk management with R” (annotated slides).
Instability hypothesis
When I was preparing for the talk, one of my ideas was to show the Google trend for searches for Minsky’s instability hypothesis. I thought it would look a lot like Figure 1.
Figure 1: My guess of interest in the instability hypothesis over time. 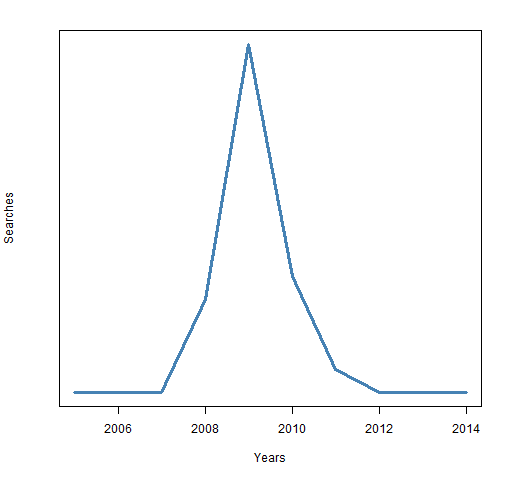 My impression is that the instability hypothesis is pretty much totally ignored except immediately following market crashes. That’s the sort of thinking that allows the pattern to continue.
Figure 2: Google trend for: minsky instability hypothesis.
The trend that I actually saw was severely different from my prior. This leads me to pretty much entirely discount the data. Part of the problem is the small number of searches at any time.
Epilogue
I’ll tell ya truly that I sometimes lie
— from “What Kinda Guy?” by Steve Forbert

[…] and embraced Minsky’s idea of an inherently unstable economy … In the years since 2008, Minsky has been forgotten and the herd has quickly drifted back to recolonise the neoclassical zone, conveniently forgetting […]