
Reminiscences of R in Finance 2016
May 29, 2016
When I announced R in Finance 2016 I talked about 2 days of conference and 50 speakers. I missed out the 3 days of sleep deprivation.
But a pleasant 3 days of sleep deprivation it was — seeing old friends and making new ones.
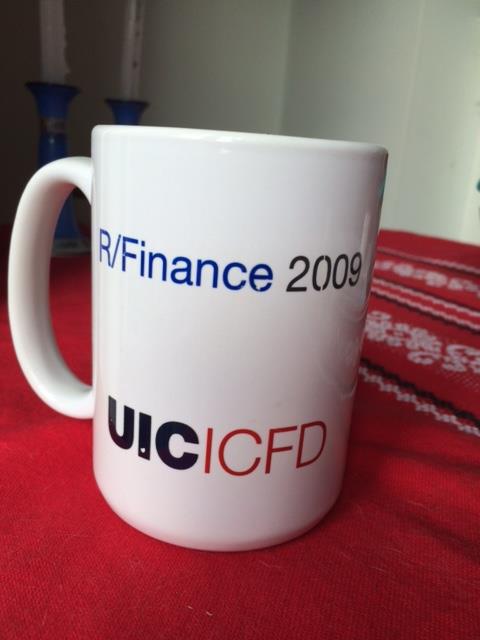
I’m not sure that Mother Mary believed me that in our house we still use the mug from the original R in Finance. Here’s proof that it still survives when so many of its comrades have perished.
I had great fun giving my presentation. The annotated slides and source for the R package are available on the Burns Statistics website.
Highlights
There were lots of good parts. I’ll limit myself to three (three is the largest number of chunks that people can easily remember).
First
Ahead by 1609.344 meters is Doug Service. Universally my experience with talks involving stochastic calculus is that my eyes glaze over before the first dW drops. At the start of Doug’s presentation my eyes were doing their cross-check preparing for landing. But the landing never happened. I have no real idea of what the equations were about — that didn’t matter: Doug made the idea of what he was doing perfectly clear.
If you insist on having formulas in your presentation (I highly discourage you from such a point of view), then you must track Doug down and make him teach you how to do it right.
Second
Second is Dirk’s update on the package interfacing Bloomberg with R:
Last year I said A.
So I lied.
Actually …
Last year I said B.
So I lied.
Actually …
Last year I said C.
So I lied.
Actually …
(You should be starting to see a pattern.)
Third
Tied for third are:
Matt Dziubinski’s high performance talk. High performance was the topic and high performance was the delivery. Clearly Matt has at least four cores dedicated to his mouth, with negligible latency.
Bryan Lewis’ politics of big data hardware implementation structures.
In the end
The taxi back to the airport was flanked by a full moon on the left and the rising sun on the right.
I was born to rock the boat
Some may sink but we will float
— from “Mutineer” by Warren Zevon

[…] Reminiscences of R in Finance 2016 [Portfolio Probe] When I announced R in Finance 2016 I talked about 2 days of conference and 50 speakers. I missed out the 3 days of sleep deprivation. But a pleasant 3 days of sleep deprivation it was seeing old friends and making new ones. Im not sure that Mother Mary believed me that in our house we still use the mug from the original R in Finance. Heres proof that it still survives when so many of its […]
[…] The Portfolio Probe website now has a blog post on the conference. And here are the slides for my […]